Most escape of water claims turn on a small number of questions: what leaked, when it started, whether it was sudden or gradual, and whether you acted reasonably once you knew. The claims that go smoothly are usually the ones where the policyholder can answer those questions with evidence rather than memory. This guide is a checklist for building that evidence, with particular attention to bathroom leaks, which are some of the most commonly disputed.
It is general guidance. Your policy wording decides what is covered, so read it alongside this. For the step-by-step trace and access process, see our trace and access claims guide.
What is an escape of water claim?
Escape of water is the insurance term for damage caused by water escaping from fixed water or heating installations: supply pipes, waste pipes, tanks, radiators, boilers, and usually fixed appliances such as washing machines and dishwashers. It sits within buildings insurance for damage to the structure, and within contents insurance for damage to belongings. Rain coming through a roof, rising groundwater and flooding are normally dealt with under different sections, if at all.
What evidence do insurers want?
Gather these as early as you can, ideally before anything is cleaned, dried or thrown away:
- Photographs and video of every affected area, wide shots and close-ups, with something in frame for scale.
- A written timeline: when you first noticed a sign, what it looked like, when it got worse, when you turned the water off and who you called.
- Water meter readings with dates, if you have a meter, and any unusual water bills.
- Boiler pressure readings with dates, if a heating leak is suspected.
- A leak detection report stating the location of the leak, the method used and the likely cause.
- Photographs of the leak itself once it is exposed, including the failed joint or pipe. Keep the failed part if the plumber removes it.
- Invoices for emergency work, with a description of what was done.
- Quotes for repair, drying and reinstatement, broken down by trade.
- A list of damaged belongings with ages and approximate values, plus receipts where you have them, for a contents claim.
- Your policy number, claim reference and a log of every call, with the name of the person you spoke to.
How do you show when the leak started?
This is the heart of many disputes. Most policies exclude damage that happened gradually, or through wear and tear, while covering sudden escapes. A hidden leak can run for weeks before anything shows, and an insurer may argue that the damage built up over time.
The Financial Ombudsman Service has published its approach: where damage was caused by an insured event such as escape of water, and the policyholder could not reasonably have known it was happening and acted promptly once they did, it is likely to consider it unfair for the insurer to rely on a gradual damage exclusion. It also says the onus is on the insurer to show it applied an exclusion reasonably.
That makes your evidence of awareness important. Useful points to record:
- where the leak was: inside a wall, under a floor, behind tiles, somewhere you could not see;
- the first visible sign and the date you saw it;
- what you did next and how quickly;
- any comment in the leak detection report about the concealed position of the pipe.
Do not guess dates or overstate how sudden it was. A consistent, honest account supported by photos is far stronger than a confident one that the evidence later contradicts.
How are bathroom leak insurance claims judged?
Bathroom claims are refused more often than most, usually for one reason: the water came from failed sealant or grout rather than from a pipe. Many policies treat sealant and grout as maintenance items, so damage from water getting past them over time may not be covered. A leak from a supply pipe, a shower valve or a waste pipe joint concealed in the floor or wall is a different matter and is more likely to fall within escape of water.
So the key evidence in a bathroom claim is what actually failed. A good investigation separates the possibilities by testing each one in turn:
| Possible source | How it is usually tested | How insurers often view it |
|---|---|---|
| Supply pipe to shower, bath or basin | Pressure test, thermal imaging, acoustic or tracer gas | Often treated as escape of water |
| Shower valve or concealed fitting | Pressure test with the valve isolated and in use | Often treated as escape of water |
| Waste pipe or trap | Controlled flood test of the tray or bath, then run to waste | Often treated as escape of water, wording varies |
| Shower tray seal, sealant or grout | Spraying the enclosure and tiles with the waste bunged or diverted | Often treated as maintenance |
| Cracked tray or failed tanking | Flood testing and moisture mapping beneath | Depends heavily on the policy and cause |
If more than one of these is failing, the report should say so, and say which one caused the damage.
What should a leak detection report contain?
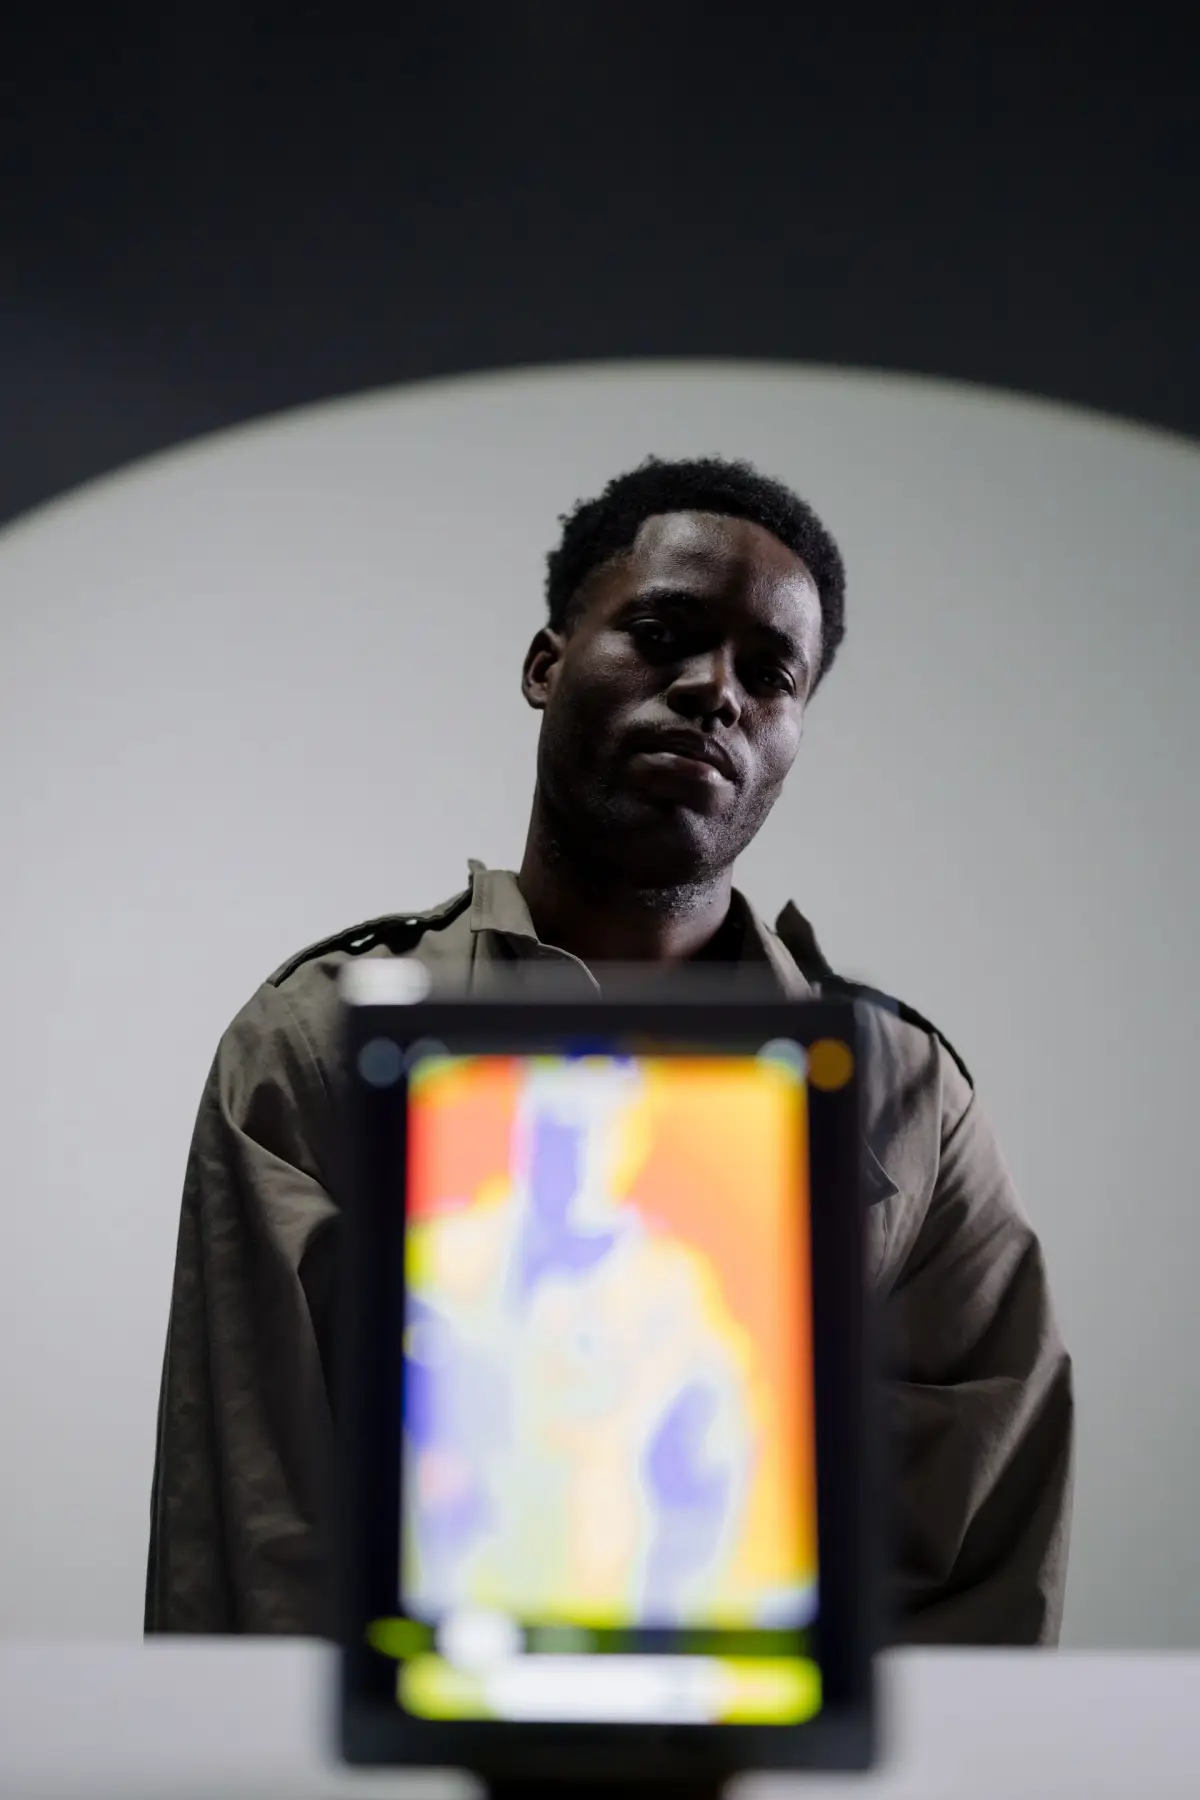
A report that answers the insurer's questions without prompting typically includes the property and date, the symptoms reported, the systems tested and the methods used, readings and images, the location of the leak marked on a plan or photo, the likely cause, and a recommended repair. Our trace and access service includes a written report with every survey, and our thermal imaging page shows the kind of images it contains.
What a report should not do is speculate beyond the evidence. A loss adjuster will read a clear "cause not established" more kindly than a confident claim that does not match what the plumber finds.
What mistakes weaken an escape of water claim?
- Carrying on using a leaking shower or bath after spotting the problem.
- Stripping out or throwing away damaged flooring or units before they are photographed.
- Opening up large areas before the insurer has agreed, when it was not needed to stop the water.
- Resealing or regrouting before the source is tested, which can hide what actually failed.
- Letting the damp sit for months after first noticing it.
- Vague or changing accounts of when the problem began.
What happens with a loss adjuster?
On larger claims the insurer may appoint a loss adjuster to inspect the damage and recommend a settlement. Have your timeline, photographs, report and quotes together in one place. Answer factually, and it is fine to say you do not know. You do not have to accept a settlement on the day, and if you disagree with the findings you can ask for the reasons in writing.
What if your claim is declined?
- Ask the insurer to confirm in writing the exact policy term it is relying on.
- Check whether your evidence addresses that point: for example, a report showing a concealed pipe failure rather than a sealant failure.
- Make a formal complaint to the insurer and include that evidence.
- The insurer normally has up to eight weeks to send a final response.
- If you are unhappy with the response, or you do not get one in time, you can refer the complaint to the Financial Ombudsman Service, normally within six months of the date of the final response.
When should you call a leak detection specialist?
Call a specialist when the source of the water is not obvious, when a bathroom leak could be either a pipe or a seal, or when your insurer asks for evidence of the location and cause. Call 020 3912 0200 and tell us what the insurer has requested.
Frequently asked questions
How do I make a successful water leak insurance claim in the UK?
Stop the water, report the claim early, photograph everything before cleaning up, keep a dated timeline, get the source located and explained in a written report, and get the insurer's agreement before major opening up or reinstatement. Keep every invoice and quote.
Is a leaking shower covered by home insurance?
It depends on what failed and on your policy. A concealed pipe, valve or waste joint failure is more likely to be covered as escape of water. Water getting past worn sealant or grout is often treated as maintenance and excluded.
Can the insurer refuse a claim because the leak was slow?
Many policies exclude gradual damage. The Financial Ombudsman Service looks at whether you could reasonably have known about the leak and whether you acted promptly, so evidence that the pipe was hidden and that you acted quickly matters.
Should I keep the broken pipe or fitting?
Yes, if the plumber removes it. Bag and label it and photograph it. It can help show whether the failure was sudden or long-standing.
How long do I have to complain to the ombudsman?
Generally within six months of the date of the insurer's final response. If eight weeks have passed and you have not had a final response, you can refer the complaint then. The final response letter should explain your right to refer the complaint.